Money & Calculations
£22,000 Loan: Monthly Payment and Total Interest at 3, 5 and 7 Years
A £22,000 loan at 6% over 5 years costs £425.32 a month and £3,519.30 in interest. Payment tables for 4%–10% and 3, 5 and 7 years, and how to scale them.
Written by Ahad NoorPublished 6 min read
A £22,000 loan at 6% over 5 years costs £425.32 a month. You repay £25,519.30 in total, which includes £3,519.30 of interest. Change the rate or the term and those figures move, so this guide gives the payment and interest for 12 combinations of rate and term, plus a shortcut for working out other loan amounts.
It follows the method in how loan repayments work, and shows what an extra £100 a month does to this particular loan. Every figure comes from the same formula as the loan repayment calculator.
Contents
What is the monthly payment on a £22,000 loan?#
It depends on the rate and the term. The worked example uses 6% over 5 years, a common combination for a car or personal loan.
Worked example: £22,000 at 6% over 5 years
Assumptions: Fixed rate of 6% a year, 60 equal monthly payments, interest charged monthly, no fees.
- Monthly payment: £425.32.
- Total repaid: 60 × £425.32 ≈ £25,519.30.
- Total interest: £25,519.30 − £22,000 = £3,519.30.
The interest is about 16% of the amount borrowed.
Monthly payment on a fixed-rate loan
Payment = P × r ÷ (1 − (1 + r)^−n)
P = 22,000; r = annual rate ÷ 12; n = months
£22,000 loan payment table: 4% to 10%, 3 to 7 years#
Each cell shows the monthly payment, with the total interest below it in the next column. Read across for a rate, and down a pair of columns for a term.
| Annual rate | 3 years: payment | 3 years: interest | 5 years: payment | 5 years: interest | 7 years: payment | 7 years: interest |
|---|---|---|---|---|---|---|
| 4% | £649.53 | £1,383.00 | £405.16 | £2,309.81 | £300.71 | £3,259.95 |
| 6% | £669.28 | £2,094.17 | £425.32 | £3,519.30 | £321.39 | £4,996.61 |
| 8% | £689.40 | £2,818.40 | £446.08 | £4,764.84 | £342.90 | £6,803.32 |
| 10% | £709.88 | £3,555.61 | £467.43 | £6,046.10 | £365.23 | £8,678.99 |
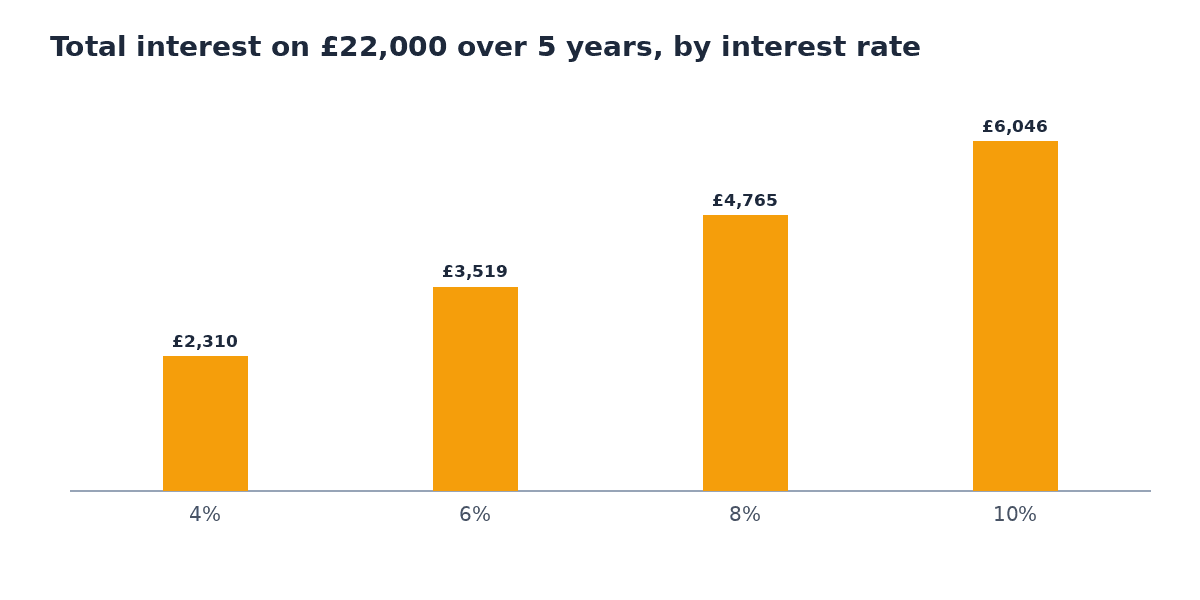
Two patterns stand out. Moving from a 3-year to a 7-year term at 6% cuts the payment by £347.89 a month but adds about £2,900 of interest. And each 2 percentage points added to the rate costs roughly £1,200 to £1,300 more interest over 5 years.
How do you work out other loan amounts?#
The payment on a fixed-rate loan is directly proportional to the amount borrowed, as long as the rate and term stay the same. Work out the payment for £1,000, then multiply.
| Term | Monthly payment per £1,000 | Total interest per £1,000 |
|---|---|---|
| 3 years | £30.42 | £95.19 |
| 5 years | £19.33 | £159.97 |
| 7 years | £14.61 | £227.12 |
Worked example: a £7,500 loan at 6% over 5 years
Assumptions: Same rate and term as the table.
- Payment per £1,000: £19.33 (rounded in the table).
- For £7,500: 7.5 × £19.33 ≈ £145, and the exact figure is £145.00.
- The same shortcut gives £231.99 for £12,000 and £1,739.95 for £90,000 over 5 years at 6%.
The per-£1,000 figures are rounded, so for an exact payment enter your own amount in the calculator.
What does an extra £100 a month do?#
Overpaying shortens the loan and cuts the interest, because every extra pound goes straight to the balance.
| Plan | Months to repay | Total interest | Interest saved | Time saved |
|---|---|---|---|---|
| Standard payment only | 60 | £3,519.30 | £0.00 | 0 months |
| £100 extra each month | 48 | £2,747.44 | £771.86 | 12 months |
The extra payments total about £4,800 over the 48 months, and the loan ends a year early. The guide How to pay off a loan early compares extra monthly payments with lump sums and covers the checks to make first.
Choosing a term#
Before you choose a rate and a term
- Decide the highest monthly payment that fits your budget with room to spare.
- Pick the shortest term whose payment is below that limit.
- Compare the total interest across at least two terms, not only the monthly payment.
- Ask whether overpayments or early settlement are allowed and what they cost.
- Check the APR and any fees when comparing lenders.
Common mistakes with loan payments#
Mistake: Comparing loans by monthly payment alone.
Instead: At 6%, the 7-year payment (£321.39) is £103.93 a month lower than the 5-year payment, but the loan costs £1,477.31 more in interest.
Mistake: Estimating interest as rate × years × amount.
Instead: 6% × 5 × £22,000 = £6,600 is nearly twice the real figure (£3,519.30), because the balance falls every month.
Mistake: Using the per-£1,000 table for a different rate or term.
Instead: The shortcut only works at the same rate and term. Enter the new rate and term in the calculator.
Mistake: Forgetting fees.
Instead: Fees raise the real cost without changing the rate. Add them to your own comparison.
Try the tool
Loan Repayment Calculator
Enter any loan amount, rate and term, then add extra payments to see how much interest you could save.
Open the Loan Repayment CalculatorFrequently asked questions#
How much is the monthly payment on a £22,000 loan?
At 6% over 5 years it is £425.32 a month. At 4% it is £405.16, at 8% it is £446.08 and at 10% it is £467.43, all over 5 years.
How much interest will I pay on a £22,000 loan over 5 years?
£3,519.30 at 6%. The interest is £2,309.81 at 4%, £4,764.84 at 8% and £6,046.10 at 10%.
How much is a £22,000 loan over 3 years?
At 6% the payment is £669.28 a month and the total interest is £2,094.17. A shorter term costs more each month but much less interest.
How do I calculate the payment on a different loan amount?
Multiply the payment per £1,000 by the number of thousands. At 6% over 5 years the payment per £1,000 is £19.33, so £12,000 costs about £231.99 a month. The rate and term must match.
How can I pay off a £22,000 loan faster?
Pay more than the required amount each month or make a lump sum payment. £100 extra a month on the 6%, 5-year loan clears it in 48 months and saves £771.86. Check your agreement for charges first.
Do these figures include fees or insurance?
No. They show principal and interest only on a fixed-rate loan. Add any arrangement fee or insurance from your own agreement to compare the total cost.
Ahad Noor
Ahad Noor builds and maintains Momentix, including its calculators, converters and the guides on this blog.
Each guide is checked against the matching Momentix tool, so the worked examples show the same figures the tool gives for the same inputs.